
The People is our section for opinions and perspectives. Submit your opinion to info@thetriibe.com.
Over the past decade, the conversation around generational wealth has become more widespread due to factors such as social media influence. Although the desire to build multi-generational financial stability is prevalent across most communities, the roadmap to get there is not universally understood. This combination of a strong desire with limited knowledge leaves many people in a vulnerable position when approaching investment opportunities.
In an attempt to promote inclusivity and provide economic opportunities, Bally’s Chicago Casino is offering minority and women investors a collective 25% equity stake in the $1.7 billion casino project. Investors must also be residents of Illinois, New York, Texas, and Florida. City employees, their family members, individuals convicted of a felony in the U.S., or those convicted of illegal gambling, are prohibited from participating. These requirements are part of the city’s broader efforts to ensure equitable economic development and address historical disparities.
On the surface, the deal appears to be an attractive investment. Qualified minority and women investors have the opportunity to buy shares in one of four classes, with initial investments ranging from $250 to $25,000:
- Class A-4, $25,000 initial investment.
- Class A-3, $5,000 initial investment with a $20,000 loan.
- Class A-2, $2,500 initial investment with a $22,5000 loan.
- Class A-1, $250 initial investment with a $24,750 loan.
Regardless of the share class purchased, each investor is essentially buying a $25,000 share. If the initial upfront investment is less than $25,000, the difference is covered through an 11% annual interest non-recourse loan that compounds quarterly. With this non-recourse loan, the investor is not liable for repayment; instead, the loan is repaid first through dividend payouts once Bally’s Chicago Casino reaches profitability. The loan must be repaid in full before the investor receives any dividend payment.
There are a significant amount of details that must be evaluated to truly understand the value of this investment:
- When will Bally’s Chicago Casino become profitable?
- What dividend payout amount per year can an investor expect?
- How long will it take to receive a return on the investment across the four classes of shares?
- Is the expected return on investment sufficient to justify the high risk nature of this investment?
The difficulty in answering these questions lies in the wide range of potential answers, which complicates the ability to provide a clear and concise understanding of the investment’s value.
Furthermore, some of the most critical details are not prominently featured in investor presentations or the community investment pitch held on the South Side of Chicago. Instead, they are buried in the SEC Form S -1 filing, an initial registration statement that a company files when it goes public. This is an intimidating document that the average individual targeted for this opportunity is unlikely to know about, let alone understand what to look for within its 251 pages of dense financial and business overviews and projections.
However, within those details, a true analysis quickly dilutes the attractiveness of this investment.
Projected Timeline to Profitability
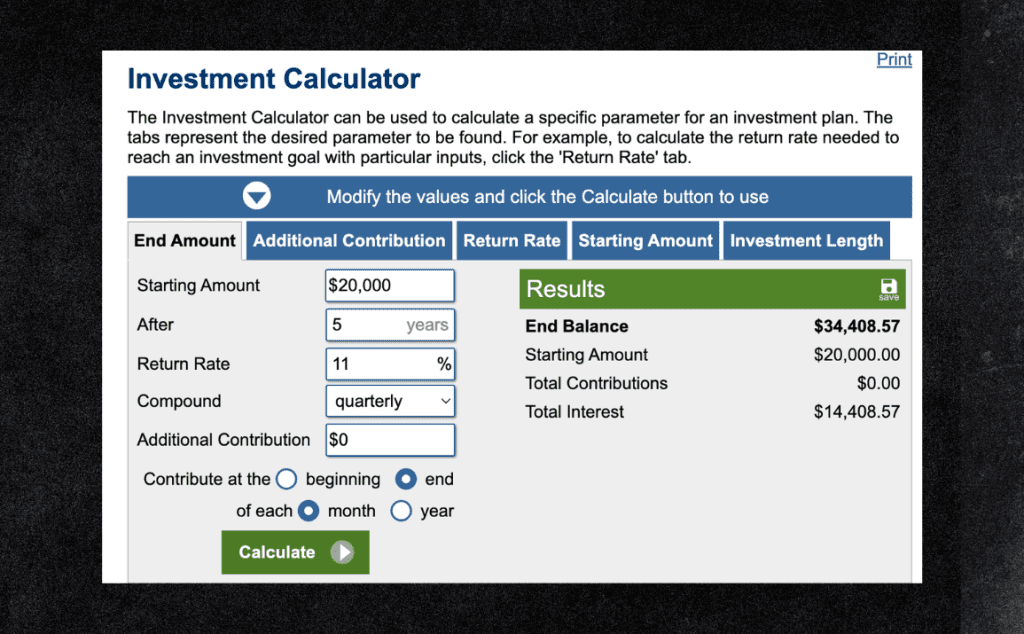
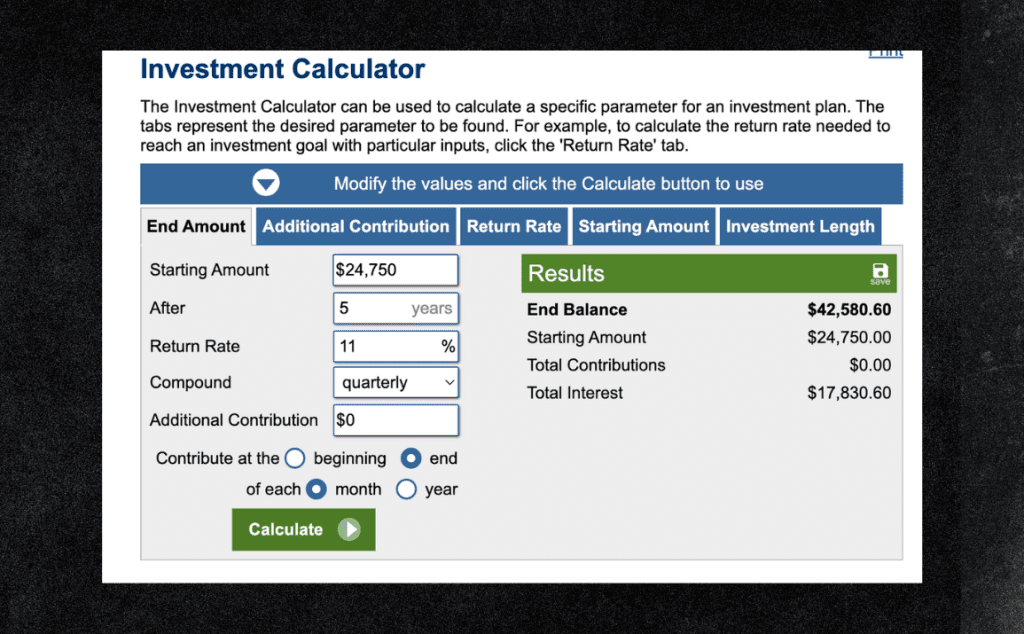
Bally’s Chicago Casino is projected to open in September 2026, but construction delays could impact this timeline. I speculate that it will likely take at least three years to achieve profitability after opening, potentially delaying dividend payouts to 5-7 years at minimum. During this period, interest accrues on the non-recourse loans. For Class A3-A1 shares, the loan balance would grow to $34,409 – $42,581 over 5 years or $42,749 – $52,901 over 7 years.
Estimated Dividend Payouts
Given the high-risk nature of this investment, adopting a conservative approach to estimating annual dividends is crucial. Considering the unproven long-term viability of the Chicago casino market, it is reasonable to assume annual returns of 2–10% of the share value, equating to $500–$2,500 in dividend payouts per year, once profitability is reached. However, at this level, repaying the initial loan is not feasible. Interest accrual would outpace dividend payouts.
Significantly higher annual payouts are required to both repay the loan and provide a return to the investor. In a scenario where profitability is achieved in 5 years, it would take an additional 30 years of annual dividend returns of 14–18% of the share value—equating to $3,531–$4,399 per year—to fully pay down a Class A3–A1 non-recourse loan. If profitability is delayed to 7 years, annual returns of 17–22%—or $4,370–$5,430 per year—would be needed over 30 years to achieve repayment and provide the investor with a return.
Given these projections, the likelihood of receiving a return in the near or mid-term for share classes requiring a loan is highly unlikely.
Lower-Risk Paths to Generational Wealth
One of the greatest investors of our time, Warren Buffett, emphasizes two important principles that provide universal guidance for the average investor:
- Invest in what you understand – stay within your “circle of competence.”
- For the average investor, invest in index funds.
These principles are a powerful reminder that successful investing doesn’t require complex strategies or one-off investment opportunities. Instead, successful investing is about understanding the business you’re investing in and focusing on simple, proven pathways to growth. For most people, this means investing in an S&P 500 index fund, which tracks the 500 largest companies in the United States. The exposure to the broader market minimizes risk, and creates a stable pathway for long-term investment growth.
Over the past 30 years, the S&P 500 has delivered an 11% average annual return, demonstrating the power of consistent, market-wide growth. This power lies in compound interest, which physicist Albert Einstein famously called the “eighth wonder of the world.” Einstein recognized that compound interest has the unique ability to exponentially grow wealth over time. With S&P 500 index funds, you tap directly into this principle when you allow your investments to grow year after year, as your returns earn returns of their own. For example, through the power of compound interest, a small investment of $250 in the S&P 500, earning an average annual return of 11%, would grow to over $1 million in 80 years with no additional contributions. Adjusted for inflation, $1 million in 80 years would be equivalent to approximately $118,000 in today’s dollars.
While no investment is entirely risk free, an index fund provides a low-cost, low-risk means of accessing the market’s overall performance. By following Buffett’s philosophy of simplicity and discipline and leveraging the magic of compound interest, investors have a straightforward way to build multi-generational wealth.
The discussion around generational wealth is one that resonates deeply, especially within historically underserved communities. The desire for economic empowerment is universal, but the path to achieving it is often clouded by misinformation and a lack of financial literacy.
When institutions like Bally’s Chicago Casino offer investment opportunities to minority and women investors, it is crucial that these individuals are equipped with the knowledge to fully understand the risks, rewards, and long-term implications of these types of investments.